
Free Preparation Discussions
 MENU

AICPA-Regulation Exam Questions
- Topic 1: Review engagement and evaluate information
- Topic 2: Planning and measurement
- Topic 3: Accounting and reporting for governmental entities.
Free AICPA CPA-Regulation Exam Actual Questions
Note: Premium Questions for CPA-Regulation were last updated On Oct. 22, 2026 (see below)
On December 1, 1997, Krest, a self-employed cash basis taxpayer, borrowed $200,000 to use in her business. The loan was to be repaid on November 30, 1998. Krest paid the entire interest amount of $24,000 on December 1, 1997. What amount of interest was deductible on Krest's 1997 income tax return?
Choice 'b' is correct. Cash basis taxpayers deduct interest in the year paid or the year to which the interest relates, whichever is later. Even though all of the interest on this loan was paid on December 1, 1997, only the interest relating to December 1997 can be deducted in 1997. The question does not give an interest rate, but because the loan is to be repaid in a lump sum at maturity, 1/12 of the interest, or $2,000 applies to each month.
Choice 'a' is incorrect. Because $2,000 of the interest relates to 1997, this amount is deductible in 1997.
Choice 'c' is incorrect. This is the amount that cannot be deducted until 1998, the year to which the interest relates. Be sure to read questions like this very carefully, because if you had simply misread the question as seeking the amount deductible in 1998, you would get the question wrong despite understanding the rule.
Choice 'd' is incorrect. Cash basis taxpayers can deduct interest in the year paid or the year to which the interest relates, whichever is later, thus 11 months of the interest will not be deductible until 1998.
Baum, an unmarried optometrist and sole proprietor of Optics, buys and maintains a supply of eyeglasses and frames to sell in the ordinary course of business. In 1999, Optics had $350,000 in gross business receipts and its year-end inventory was not subject to the uniform capitalization rules. Baum's 1999 adjusted gross income was $90,000 and Baum qualified to itemize deductions. During 1999, Baum recorded the following information:
Business expenses:
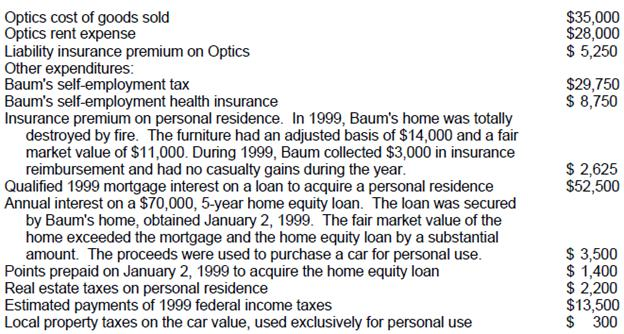
What amount should Baum report as 1999 net earnings from self-employment?
Choice 'd' is correct. Baum should report $281,750 as 1999 net earnings from self-employment (line 12 of the Form 1040), calculated as follows:
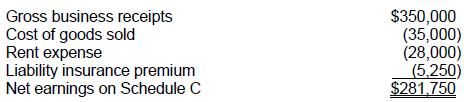
Choices 'a', 'b', and 'c' are incorrect. Self-employment tax and self-employment health insurance expenses are adjustments from total gross income. They are not deducted from self-employment earnings (i.e., not reported net on line 12 of the Form 1040).
Note: There are many distracters in this question, all relating to items that are either deductible as part of itemized deductions or not deductible. Be careful to read the requirement of the question before spending unnecessary time on the question. The statement that Baum's year-end inventory was not subject to the uniform capitalization rules is a distracter as well. There is not enough information given in the facts to apply the rules if he had been subject to them.
Darr, an employee of Sorce C corporation, is not a shareholder. Which of the following would be included in a taxpayer's gross income?
Choice 'd' is correct. An individual receiving common stock for services rendered must recognize the fair market value as ordinary income. Any dividends received on that stock would also result in income recognition.
Choice 'a' is incorrect. Employer-provided medical insurance is a tax-free fringe benefit.
Choices 'b' and 'c' are incorrect. Gifts and inheritances are both tax-free to the recipient. (Remember tax is often paid by the person giving the gift or the estate at death.)
Adams owns a second residence that is used for both personal and rental purposes. During 2001, Adams used the second residence for 50 days and rented the residence for 200 days. Which of the following statements is correct?
Choice 'c' is correct. Because the second property was personally used more than 14 days, any net loss from the rental of the property will be disallowed.
All related expenses must be prorated between the personal use portion and the rental activity portion.
Prorated depreciation is permitted for the rental activity.
John and Mary were divorced in 1991. The divorce decree provides that John pay alimony of $10,000 per year, to be reduced by 20% on their child's 18th birthday. During 1992, John paid $7,000 directly to Mary and $3,000 to Spring College for Mary's tuition. What amount of these payments should be reported as income in Mary's 1992 income tax return?
Choice 'b' is correct. Alimony would be income to Mary while child support would not. Funds qualify as child support only if 1) a specific amount is fixed or is contingent on the child's status (e.g., reaching a certain age), 2) it is paid solely for the support of minor children, and 3) it is payable by decree, instrument or agreement. The actual use of the funds is irrelevant to the issue. In this case, $2,000 (20% $10,000) qualifies as child support. The other $8,000 is alimony, which would be income to Mary.
Choice 'a' is incorrect. Take 80% of the $10,000 paid, not 80% of the $7,000 received by Mary.
Choice 'c' is incorrect. Only $8,000 would be alimony per the divorce decree (80% $10,000).
Choice 'd' is incorrect. The 20% reduction when the child turns 18 makes 20% of the $10,000 payment, or $2,000, child support, which is nontaxable to Mary.
- Select Question Types you want
- Set your Desired Pass Percentage
- Allocate Time (Hours : Minutes)
- Create Multiple Practice tests with Limited Questions
- Customer Support
Nicolas Marino
20 days agoPatricia Wright
2 months agoYui Huang
2 months agoRobert Lewis
3 months agoSamira Hussain
3 months agoBetty Evans
4 months agoMonica Mitchell
5 months agoEric Johnson
6 months agoJohn Lee
6 months agoRachel Reed
6 months agoStephanie King
6 months agoMonica Turner
5 months agoBrenda Peterson
5 months agoHeather Carter
6 months agoKanisha
7 months agoRosann
7 months agoYuriko
7 months agoFletcher
8 months agoBette
8 months agoStephane
8 months agoJames
8 months agoSherly
9 months agoJill
9 months agoChau
9 months agoKanisha
9 months agoRoxane
10 months agoFlorinda
10 months agoAlecia
10 months agoSherita
11 months agoOra
11 months agoTammy
11 months agoMari
11 months agoKris
11 months agoLili
12 months agoTricia
1 year agoAshley
1 year agoDick
1 year agoLettie
1 year agoBilly
1 year agoAlpha
1 year agoBarabara
1 year agoPenney
1 year agoTony
1 year agoBasilia
1 year agoLevi
1 year agoWava
1 year agoMaryann
2 years agoDaren
2 years agoKati
2 years agoEveline
2 years agoVannessa
2 years agoAudry
2 years agoJaclyn
2 years agoDaniela
2 years agoShawn
2 years agoRolf
2 years agoAngella
2 years agoJettie
2 years agoJulie
2 years agoAlfreda
2 years agoDetra
2 years agoBettye
2 years agoSage
2 years agoDortha
2 years agoAnnamaria
2 years agoAshley
2 years agoMatthew
2 years agoMiriam
2 years agoMarshall
2 years agoYuette
2 years agoHubert
2 years agoTiara
2 years agoBarrie
2 years agoGianna
2 years agoEnola
2 years agoElina
2 years agoCarman
2 years agoErasmo
2 years agoGlory
2 years agoGwenn
2 years agoDaren
2 years agoCraig
2 years agoLisbeth
2 years ago