
 MENU

Which of the following insurances would provide cover in the eventuality that your supplier's place of business flooded and this affected your deliveries?
Suggested Answer: A
Get Premium L5M2 Questions
as Interactive Web-Based Practice Test or PDF
Real Exam Format
Detailed Explanations
Instant Access
Get Your Practice Test
The correct answers are as follows:
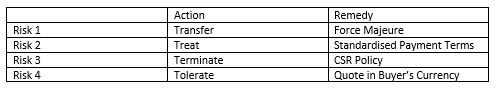
CSR= Corporate Social Responsibility
46 comments · newest first
EU
Eun
11 months ago
Nah, property insurance wouldn’t cover that situation.
RO
Rosenda
12 months ago
Really? I’m surprised this isn’t more straightforward.
OW
Owen
12 months ago
Wait, is public liability insurance not an option here?
AL
Alita
1 year ago
I thought it was A, business interruption insurance?
EV
Evangelina
1 year ago
Definitely B, contingent business interruption insurance covers that.
CH
Cherelle
1 year ago
I thought property insurance was more about covering physical assets, so I don't think that's the right choice for this scenario.
MA
Maryann
1 year ago
I’m leaning towards option B too, but I vaguely recall something about public liability insurance not being relevant here.
LA
Lashonda
1 year ago
I remember studying business interruption insurance, but I feel like that only covers your own business losses, not someone else's.
AN
Anika
1 year ago
I think it might be contingent business interruption insurance since it specifically covers losses due to a supplier's issues, but I'm not entirely sure.
JU
Juan
1 year ago
Hmm, I'm a bit unsure about this one. The PDCA cycle is related to continuous improvement, but I'm not sure if that's the exact concept behind it. I'll have to think this through carefully.
CU
Curt
1 year ago
I'm leaning towards asking the Scrum Master to secure additional time and resources. This new requirement could really impact our sprint.
MI
Mica
1 year ago
Okay, I think I've got a handle on this. The key is understanding how the mobile market has driven more iterative, collaborative development. I'll focus on how that changes the dynamic between devs and testers.
MI
Michael
1 year ago
This looks like a tricky Nmap UDP scan question. I'll need to think through the possible responses carefully.
SH
Sharen
1 year ago
Okay, let me break this down. Data masking is used for things like testing and enforcing least privilege, but not for authentication or remote access. I think I've got it.
DO
Doyle
1 year ago
I think this question is asking about the security features of IEEE 802.1X, so I'll need to focus on understanding how that protocol works to control network access.
MA
Maryrose
2 years ago
B) contingent business interruption insurance is the way to go. Gotta protect ourselves from those unexpected supplier issues, you know?
JE
Jenise
1 year ago
D) property insurance wouldn't help with supplier issues, so B) is the best choice.
GR
Graciela
1 year ago
B) I agree, contingent business interruption insurance seems like the best option in this case.
GE
Gearldine
1 year ago
A) business interruption insurance wouldn't cover that specific scenario.
LE
Leoma
2 years ago
Haha, D) property insurance - is that a joke? Maybe they should just ask which insurance covers 'Acts of God' instead.
BE
Bernadine
1 year ago
D) property insurance wouldn't cover that scenario
RO
Rosita
1 year ago
B) contingent business interruption insurance would be the right choice
DI
Dick
2 years ago
A) business interruption insurance would cover that
MA
Marcelle
2 years ago
I'm not sure, but I think A) business interruption insurance could also provide cover in this situation.
TE
Tesha
2 years ago
I agree with Shaquana, because it covers disruptions caused by suppliers.
QU
Queen
2 years ago
D) property insurance? Really? How's that going to help if our supplier's place floods? I think they need to try harder on the answer choices.
MA
Mary
1 year ago
D) property insurance would cover the physical damage to the supplier's place due to flooding.
KA
Kandis
1 year ago
C) public liability insurance would not cover the loss of income due to the supplier's place flooding.
DE
Deeanna
1 year ago
B) contingent business interruption insurance would cover the loss of income due to the supplier's place flooding.
ST
Stephen
1 year ago
A) business interruption insurance would cover the loss of income due to the supplier's place flooding.
NI
Nichelle
1 year ago
D) property insurance would cover the physical damage to the supplier's place due to flooding.
JE
Jesus
1 year ago
C) public liability insurance would not cover the loss of income due to the supplier's place flooding.
CO
Cordell
1 year ago
B) contingent business interruption insurance would cover the loss of income due to the supplier's place flooding.
VI
Vincent
1 year ago
A) business interruption insurance would cover the loss of income due to the supplier's place flooding.
SH
Shaquana
2 years ago
I think the answer is B) contingent business interruption insurance.
MA
Marlon
2 years ago
I'm not sure, but I think A) business interruption insurance could also provide cover in this situation.
PE
Peggie
2 years ago
I agree with Timothy, because it covers disruptions caused by suppliers.
PE
Peggie
2 years ago
I'm going with B as well. Can't afford to be left high and dry if our suppliers can't deliver the goods.
AL
Alecia
2 years ago
B) contingent business interruption insurance
MA
Mary
2 years ago
A) business interruption insurance
MI
Micheal
2 years ago
B) contingent business interruption insurance seems like the right choice here. It's specifically designed to cover us if our suppliers' operations are disrupted.
JE
Jettie
1 year ago
D) Property insurance is more for physical damage to our own property, not our suppliers'.
AL
Alpha
2 years ago
C) Public liability insurance wouldn't cover supply chain disruptions like this.
BR
Britt
2 years ago
B) Yes, contingent business interruption insurance is the right choice in this scenario.
LI
Lina
2 years ago
A) business interruption insurance would cover us if our own operations were disrupted, not our suppliers'.
TI
Timothy
2 years ago
I think the answer is B) contingent business interruption insurance.