Deal of The Day! Hurry Up, Grab the Special Discount - Save 25% - Ends In 00:00:00 Coupon code: SAVE25

Free Preparation Discussions
 MENU

CIMAPRA19-F03-1 Exam - Topic 1 Question 69 Discussion
Actual exam question for
CIMA's
CIMAPRA19-F03-1 exam
Question #: 69
Topic #: 1
[All CIMAPRA19-F03-1 Questions]
Topic #: 1
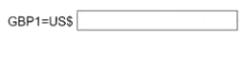
D has US$10 million to invest over 12 months in either USS or GBP Its options are to invest in USS at the present USS interest rate of 10 18%. or to convert the USS to GBP at the spot rate GBP1 =US$1 61 and invest in GBP at an interest rate of 6.4%.
According to the interest rate parity theory, what will the one year forward rate be?
Give your answer to three decimal places.
Suggested Answer:
A
Howard
10 months agoGlory
10 months agoWillow
10 months agoJill
11 months agoLashaunda
11 months agoAja
11 months agoBarb
11 months agoKrystal
11 months agoPete
11 months agoEdmond
11 months agoChristoper
11 months agoMy
11 months ago