
 MENU

Charles Mabry manages a portfolio of equity investments heavily concentrated in the biotech industry. He just returned from an annual meeting among leading biotech analysts in San Francisco. Mabry and other industry experts agree that the latest industry volatility is a result of questionable product safety testing methodologies. While no firms in the industry have escaped the public attention brought on by the questionable safety testing, one company in particular is expected to receive further attention---Biological Instruments Corporation (BIC), one of several long biotech positions in Mabry's portfolio. Several regulatory agencies as well as public interest groups have heavily criticized the rigor of BIC's product safety testing.
In an effort to manage the risk associated with BIC, Mabry has decided to allocate a portion of his portfolio to options on BIC's common stock. After surveying the derivatives market, Mabry has identified the following European options on BIC common stock:
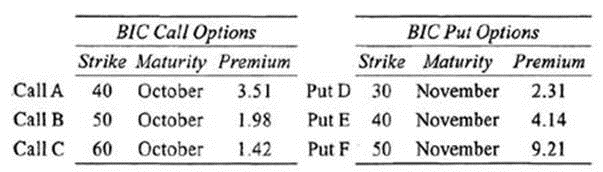
Mabry wants to hedge the large BIC equity position in his portfolio, which closed yesterday (June 1) at $42 per share. Since Mabry is relatively inexperienced with utilizing derivatives in his portfolios, Mabry enlists the help of an analyst from another firm, James Grimell.
Mabry and Grimell arrange a meeting in Boston where Mabry discusses his expectations regarding the future returns of BIC's equity. Mabry expects BIC equity to make a recovery from the intense market scrutiny but wants to provide his portfolio with a hedge in case BIC has a negative surprise. Grimell makes the following suggestion:
"If you want to avoid selling the BIC position and are willing to earn only the risk-free rate of return, you should sell calls and buy puts on BIC stock with the same market premium. Alternatively, you could buy put options to manage the risk of your portfolio. I recommend waiting until the vega on the options rises, making them less attractive and cheaper to purchase."
If the premium on Put D on November 1 is $3.18, which of the following has most likely occurred?
The premium on Put D has risen from $2.31 to $3.18 and there is srill time left until expiration. Therefore, the increase in value must have come from either a decrease in stock price, an increase in volatility, or both of these events. Choice A would be correct if the option was at expiration and the $3.18 represented only intrinsic value. Since we are not yet at the expiration date, the stock price must be above $26.82. A negative earnings surprise would most likely cause a drop in the market price of the stock. Since there is no indication of the exact amount of the drop in price, the premium observed is a possibility. A decrease in BIG volatility would reduce the put premium, not increase it. (Study Session 17, LOS 60.d)