
Deal of The Day! Hurry Up, Grab the Special Discount - Save 25% - Ends In 00:00:00 Coupon code: SAVE25
Welcome to Pass4Success

- Free Preparation Discussions

AIWMI CCRA-L2 Exam - Topic 4 Question 131 Discussion

Posted by Simona on Aug 12, 2026 at 09:43 AM

Scott is a credit analyst with one of the credit rating agencies in Indi

a. He was looking in Oil and Gas Industry companies and has presented brief financials for following 4 entities:
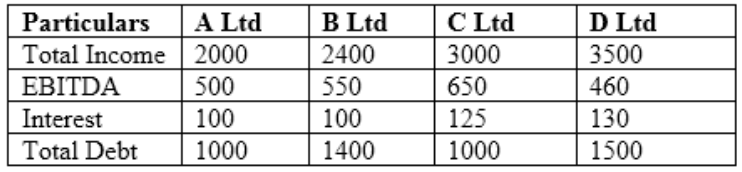
From the data given below, calculate the standard deviation of the credit portfolio assuming that facility's exposure is known with certainty, customer defaults and LGDs are independent of one another and LGDs are independent across borrower(s).

Credit Facility A -- Loss Equivalent Exposure of $60m, expected Default frequency of 1.5%, loss given default

of 30%, Std Deviation of LGD -- 5% and Correlation to portfolio -- 0.10

Credit Facility B -- Loss Equivalent Exposure of $25m, expected Default frequency of 2%, loss given default of 12%, Std Deviation of LGD -- 12% and Correlation to portfolio -- 0.45

Credit Facility C -- Loss Equivalent Exposure of $15m, expected Default frequency of 5%, loss given default of 85%, Std Deviation of LGD -- 18% and Correlation to portfolio -- 0.22

Suggested Answer: B

Get Premium CCRA-L2 Questions as Interactive Web-Based Practice Test or PDF Real Exam Format Detailed Explanations Instant Access Get Your Practice Test
16 comments · newest first
MA
Mariann 4 days ago
This question is tricky! I feel a bit overwhelmed.
SO
Solange 9 days ago
I’m not sure. I might go with C. The LGD is really high for Facility C.
ED
Edda 15 days ago
I agree with Ava. A makes sense with the high exposure.
AL
Alisha 20 days ago
I’m confused about the correlation part. It complicates things.
EM
Emilio 25 days ago
I’m leaning towards B. It feels more reasonable with the data provided.
TH
Therese 1 month ago
I think A is the right answer. The calculations seem to point there.
ME
Mendy 1 month ago
This question is tricky! I feel a bit overwhelmed.
MA
Marget 1 month ago
Wow, I didn't expect the LGD for C to be that high!
LA
Laurene 2 months ago
I disagree, B seems more plausible to me.
AM
Ammie 2 months ago
Wait, how does C have such a high default frequency?
PE
Pearlene 2 months ago
I think A is the right answer.
TI
Titus 2 months ago
Standard deviation calculations can be tricky!
GL
Glenn 2 months ago
I think the standard deviation is influenced by the correlation values, but I can't recall the exact formula we used.
SH
Shenika 2 months ago
I feel a bit lost with the LGD and correlation factors. Did we cover how to combine those in our calculations?
LI
Lino 3 months ago
This question reminds me of a similar practice problem we did on credit risk. I think we need to consider the exposure and default rates carefully.
IR
Iraida 3 months ago
I remember we practiced calculating standard deviation in class, but I'm not sure how to apply it with the correlations here.
0/2000 characters

Save Cancel