
 MENU

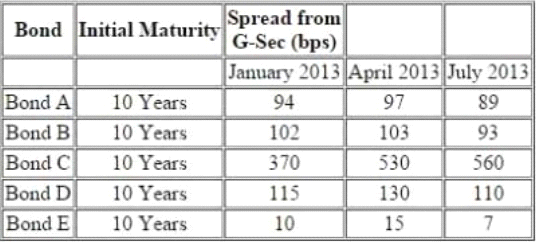
The following information pertains to bonds:
Further following information is available about a particular bond 'Bond F'
There is a 10.25% risky bond with a maturity of 2.25% year(s) its current price is INR105.31, which corresponds to YTM of 9.22%. The following are the benchmark YTMs.
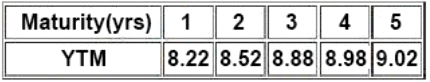
Compute interpolated spread for Bond F based on the information provided in the vignette:
Suggested Answer: A
Get Premium CCRA-L2 Questions
as Interactive Web-Based Practice Test or PDF
Real Exam Format
Detailed Explanations
Instant Access
Get Your Practice Test
9 comments · newest first
VI
Vince
1 year ago
Wait, how can the YTM be lower than the coupon rate?
FR
Francisca
1 year ago
10.25% coupon rate is pretty high for a risky bond!
MA
Mari
1 year ago
Not sure about that, I’m leaning towards 0.61%.
GA
Galen
1 year ago
I think the interpolated spread is 1.64%.
RU
Ruth
1 year ago
Bond F has a YTM of 9.22%.
JA
Jackie
1 year ago
Okay, the key here is to reduce query execution time. I'll choose the two queries with the highest execution times, which are QN = 3 and QN = 5.
ME
Mel
1 year ago
I'm not entirely sure about this one. I'll need to think through the factors that influence AP placement and signal attenuation in a high-density wireless network. Maybe I can eliminate some of the options and narrow it down.
LA
Lashaun
1 year ago
Poisoning doesn't seem right here, but I can't pinpoint why. I've seen questions where techniques are trialed with data manipulation.
WI
Willetta
1 year ago
It doesn't; B is misleading.