
Free Preparation Discussions
 MENU

AICPA-Financial Exam Questions
- Topic 1: Financial Statement Concepts
- Topic 2: General Principles of Financial Statement Presentation and Accounting Policies
- Topic 3: Special Accounting Considerations for Certain Financial Assets and Liabilities.
Free AICPA CPA-Financial Exam Actual Questions
Note: Premium Questions for CPA-Financial were last updated On Oct. 23, 2026 (see below)
The effect of a material transaction that is infrequent in occurrence but not unusual in nature should be presented separately as a component of income from continuing operations when the transaction results in a:
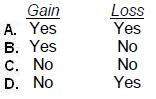
Choice 'a' is correct, Yes - Yes. A material transaction that is 'infrequent in occurrence' but not 'unusual in nature' should be presented separately as a component of 'income from continuing operations' when the transaction results in a gain or loss.
At December 31, 1998, Off-Line Co. changed its method of accounting for demo costs from writing off the costs over two years to expensing the costs immediately. Off-Line made the change in recognition of an increasing number of demos placed with customers that did not result in sales. Off-Line had deferred demo costs of $500,000 at December 31, 1997, $300,000 of which were to be written off in 1998 and the remainder in 1999. Off-Line's income tax rate is 30%. In its 1998 financial statements, what amount should Off-Line report as cumulative effect of change in accounting principle?
Choice 'a' is correct. When a change in accounting principle is considered inseparable from a change in estimate, the change is handled as a change in estimate - prospectively. No cumulative effect adjustment is made.
Choices 'b', 'c', and 'd' are incorrect since no cumulative effect adjustment is made.
Due to a decline in market price in the second quarter, Petal Co. incurred an inventory loss. The market price is expected to return to previous levels by the end of the year. At the end of the year the decline had not reversed. When should the loss be reported in Petal's interim income statements?
Choice 'd' is correct. When the loss is probable and estimable, the expected loss must be recorded in full. This loss becomes such at the end of the fourth quarter. Therefore, the inventory must be valued on the year-end at the lower of cost or market, recognizing the loss at that time.
Choice 'a' is incorrect. Expected losses must be recorded in full when the loss is probable and estimable and not ratably over several quarters.
Choice 'b' is incorrect. Expected losses must be recorded in full when the loss is probable and estimable and not ratably over several quarters.
Choice 'c' is incorrect. Since the loss is not probable at the end of the second quarter, no amount should be recognized at that time.
An extraordinary item should be reported separately on the income statement as a component of income:
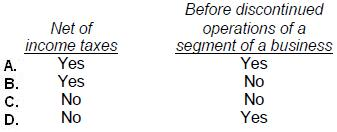
Choice 'b' is correct, Yes - No. An extraordinary item should be reported separately on the income statement as a component of income:
Yes - net of income taxes.
No - after (not before) 'discontinued operations of a segment of a business.'
On January 2, 20X5, to better reflect the variable use of its only machine, Holly, Inc. elected to change its method of depreciation from the straight-line method to the units of production method. The original cost of the machine on January 2, 20X3, was $50,000, and its estimated life was 10 years. Holly estimates that the machine's total life is 50,000 machine hours. Machine hours usage was 8,500 during 20X4 and 3,500 during 20X3.
Holly's income tax rate is 30%. Holly should report the accounting change in its 20X5 financial statements as a(n):
Choice 'd' is correct. A change in the method of depreciation is now considered to be both a change in method and a change in estimate. These changes should be accounted for as changes in estimate and handled prospectively. The new depreciation method should be used as of the beginning of the year of change and should start with the current book value of the underlying asset. No retroactive or retrospective calculations should be made, and no adjustment should be made to retained earnings.
The cumulative effect treatment on the income statement was the treatment of most changes in accounting principle prior to SFAS No. 154. The adjustment to beginning retained earnings is the treatment now given to changes in accounting principle by SFAS No. 154. However a change in depreciation method is no longer accounted for as a change in accounting principle.
Choices 'a', 'b', and 'c' are incorrect, per the above Explanation: .
- Select Question Types you want
- Set your Desired Pass Percentage
- Allocate Time (Hours : Minutes)
- Create Multiple Practice tests with Limited Questions
- Customer Support
Linda Jones
7 days agoAstrid Petrov
1 month agoRyan King
2 months agoErik Dupont
2 months agoOlivia Adams
3 months agoKunal Singh
3 months agoHarold Scott
4 months agoPriya Nair
4 months agoJennifer Allen
5 months agoCarol Murphy
6 months agoDonna Murphy
6 months agoKenneth Evans
6 months agoAnthony Taylor
6 months agoDaniel Green
6 months agoRachel Rogers
6 months agoStevie
7 months agoDarnell
7 months agoBethanie
7 months agoMargart
8 months agoShenika
8 months agoClaribel
8 months agoDorian
8 months agoAn
9 months agoFrederica
9 months agoMaxima
9 months agoAlpha
9 months agoLatricia
10 months agoAlesia
10 months agoGlory
10 months agoBrittani
11 months agoGeorgeanna
11 months agoLouis
11 months agoDelbert
11 months agoValentin
11 months agoMarlon
12 months agoCorinne
1 year agoNorah
1 year agoGlory
1 year agoJenelle
1 year agoLucy
1 year agoBrunilda
1 year agoAntonio
1 year agoNida
1 year agoSunny
1 year agoNina
2 years agoJackie
2 years agoLouvenia
2 years agoArlyne
2 years agoAlbert
2 years agoMelvin
2 years agoWhitley
2 years agoJordan
2 years agoMalcolm
2 years agoJuliann
2 years agoLashaunda
2 years agoIvette
2 years agoSherita
2 years agoXenia
2 years agoKasandra
2 years agoArlyne
2 years agoTamra
2 years agoEloisa
2 years agoJeff
2 years agoAlbina
2 years agoVirgie
2 years agoWilliam
2 years agoFairy
2 years ago