Deal of The Day! Hurry Up, Grab the Special Discount - Save 25% - Ends In 00:00:00 Coupon code: SAVE25

Free Preparation Discussions
 MENU

AAFM GLO_CWM_LVL_1 Exam - Topic 5 Question 50 Discussion
Actual exam question for
AAFM's
GLO_CWM_LVL_1 exam
Question #: 50
Topic #: 5
[All GLO_CWM_LVL_1 Questions]
Topic #: 5
Consider two stocks, A and B
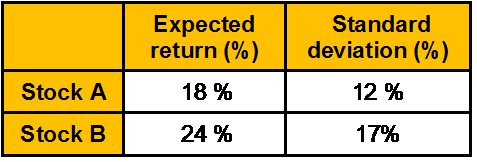
The returns on the stocks are perfectly negatively correlated.
What is the expected return of a portfolio comprising of stocks A and B when the portfolio is constructed to drive the standard deviation of portfolio return to zero?
Suggested Answer:
B
Irma
10 months agoReena
10 months agoHelene
11 months agoBillye
11 months agoSoledad
11 months agoMacy
11 months agoPenney
11 months agoEric
11 months agoKristofer
11 months agoRosina
11 months agoHildegarde
11 months agoLottie
12 months ago